The Bureau of Internal Revenue (BIR) has officially released the implementing guidelines for mandatory electronic invoicing, accelerating the country’s tax administration digitalization efforts ahead of the December 31 deadline for covered taxpayers.
Issued on September 22, Revenue Memorandum Circular No. 98-2026 sets the framework enforcing electronic invoicing requirements under Revenue Regulations Nos. 8-2022 and 11-2025, as amended by RR No. 26-2025.
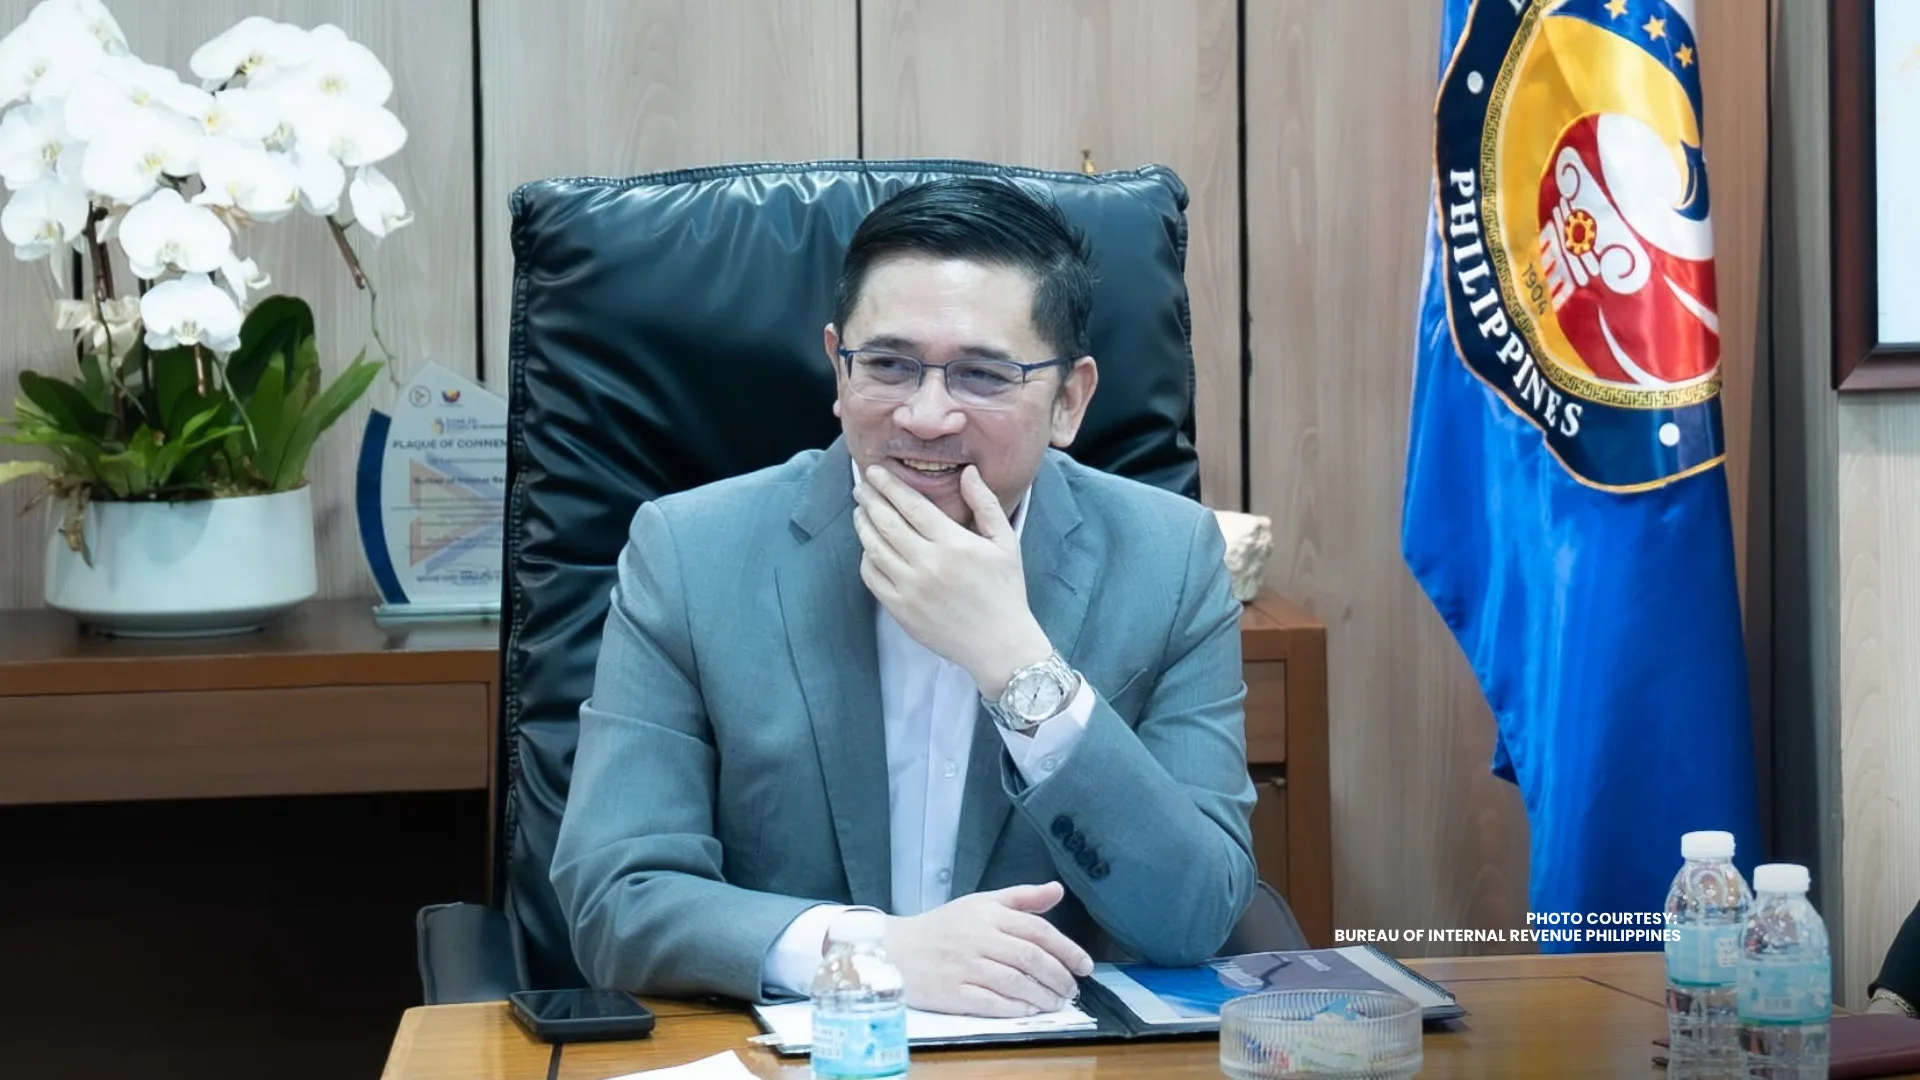
BIR Commissioner Charlito Martin R. Mendoza emphasized that establishing these rules enables the revenue agency to launch the digital shift while making necessary adjustments during operational rollout.
“With these rules in place, we can now move into implementation and refine the framework as needed. Our goal is to make electronic invoicing workable for taxpayers while laying a stronger foundation for the continued digitalization of tax administration,” Mendoza said.
Mandated taxpayers must begin issuing compliant electronic invoices on or before December 31. The circular applies to specific taxpayer classifications:
E-Commerce & Digital Transactions: Small, medium, and large taxpayers engaged in e-commerce or online business operations.
Large Taxpayers: Entities registered under the Large Taxpayers Service (LTS) and large taxpayers covered under the Ease of Paying Taxes framework.
Computerized Systems Users: Taxpayers utilizing computerized accounting systems (CAS), computerized books of accounts with accounting records, or other computerized invoicing software.
The bureau clarified that micro-sized taxpayers are completely exempt from the mandatory electronic invoicing requirement.
To satisfy the requirements, covered businesses may develop in-house software solutions, acquire commercial invoicing applications, or hire accredited Electronic Invoicing Service Providers. The BIR noted it will release a separate directive governing Electronic Invoicing Service Providers within the month.
Commissioner Mendoza made a clear distinction between issuing digital invoices to customers and reporting real-time sales data directly to the bureau.
“Electronic invoicing and electronic sales reporting are separate requirements. For now, taxpayers should focus on complying with the electronic invoicing rules. Electronic sales reporting will follow once the BIR issues the separate implementing policies and procedures for it,” he said.
The guidelines, which went into effect immediately upon issuance, reflect feedback gathered during a BIR-PMSG public consultation held on August 25 at the BIR National Office, where tax officials met with private-sector stakeholders to refine operational details.
“Electronic invoicing is a huge step toward revolutionizing invoicing and tax administration in the Philippines. It will change how businesses document transactions, how tax information is generated, and how the BIR uses data to build a more modern and efficient tax system,” Mendoza said.